What if the most dangerous portfolio is not the one with the riskiest token, but the one whose risks cannot be seen together? In DeFi, an investor may hold assets across Ethereum and several EVM-compatible networks, supply liquidity through multiple protocols, approve spending rights to unfamiliar contracts, and keep a portion of capital in externally owned accounts or smart-contract positions. A conventional balance view can make that arrangement look diversified. Operationally, it may be concentrated in one bridge, one stablecoin, one oracle design, or one compromised permission.
Portfolio tracking therefore has a more demanding job than adding token balances. It must help users reconstruct exposure, understand how positions behave, and identify what could go wrong before a transaction is signed. For US-based DeFi users managing volatile assets across chains, the central question is not simply “How much do I own?” It is “Which claims, permissions, dependencies, and execution assumptions make up my current risk?”
Tracking balances is not the same as understanding exposure
The first misconception to correct is that a portfolio tracker is a neutral accounting tool. On-chain data is transparent, but transparency does not automatically produce a meaningful risk picture. A wallet may show a dollar value for a liquidity-provider position while hiding its dependence on pool composition, fee income, impermanent loss, withdrawal conditions, and the solvency of any associated protocol. A token balance may appear stable while its value depends on a redemption mechanism, collateral ratio, or market liquidity that can change rapidly.
A useful distinction is between inventory and exposure. Inventory describes what an address appears to hold. Exposure describes the economic consequences of holding it. For example, two wallets might each display $10,000 in assets. One may hold liquid ether and dollar-denominated tokens in separate accounts. The other may hold a leveraged lending position whose collateral, debt, liquidation threshold, and oracle feed are all linked. Their displayed balances are similar; their failure modes are not.
Multi-chain activity adds another layer. The same user may own an asset natively on one network, as a wrapped representation on another, and through a protocol receipt token on a third. Treating these as interchangeable can obscure bridge risk and redemption risk. A tracker should distinguish chain, contract address, token standard, protocol position, and economic function. It should also identify whether an asset is immediately transferable, subject to a lockup, dependent on a withdrawal queue, or valued using a thin market.
This is why portfolio review should begin with a dependency map rather than a ranking of returns. Ask which assets depend on the same stablecoin, bridge, oracle, validator set, lending market, or administrative key. Correlation is not limited to price movements. A shared technical dependency can create losses across assets that appear unrelated during normal market conditions.
Security risk begins before the transaction is confirmed
Wallet security is often described as a custody problem: protect the seed phrase, use a hardware device, and avoid suspicious websites. Those practices matter, but they address only part of the attack surface. In DeFi, a transaction can be authorized by the legitimate owner and still produce an unintended result because the user misunderstood the contract call, the token approval, the recipient, or the amount being exposed.
Transaction simulation is valuable because it shifts review from abstract calldata to an attempted outcome. Instead of asking only whether a transaction can be signed, the user can examine what the wallet expects to change: which assets leave the account, which assets arrive, what approvals are created, and whether a position is opened or closed. Simulation is not proof that a transaction is safe. It is a diagnostic layer that can reveal a mismatch between the user’s intention and the transaction’s likely effects.
That limitation is important. Simulations depend on the state of the relevant network and on the ability of the simulation environment to reproduce contract behavior. A transaction may encounter a different block state, changing prices, liquidity, or eligibility conditions. Some contracts may behave differently under unusual inputs, and a benign-looking token approval can remain dangerous after the immediate transaction is complete. Simulation reduces uncertainty; it does not eliminate the need for contract, allowance, and counterparty judgment.
For practical risk management, treat each transaction as a change to the portfolio’s permission structure as well as its balance sheet. An approval grants a contract authority to move specified tokens, sometimes for an amount and duration that exceed the user’s immediate need. A signature may authorize an off-chain order or permit that is executed later. A wallet with clear warnings and readable simulation results can improve the decision process, particularly when the user operates across many EVM chains and cannot rely on memory alone.
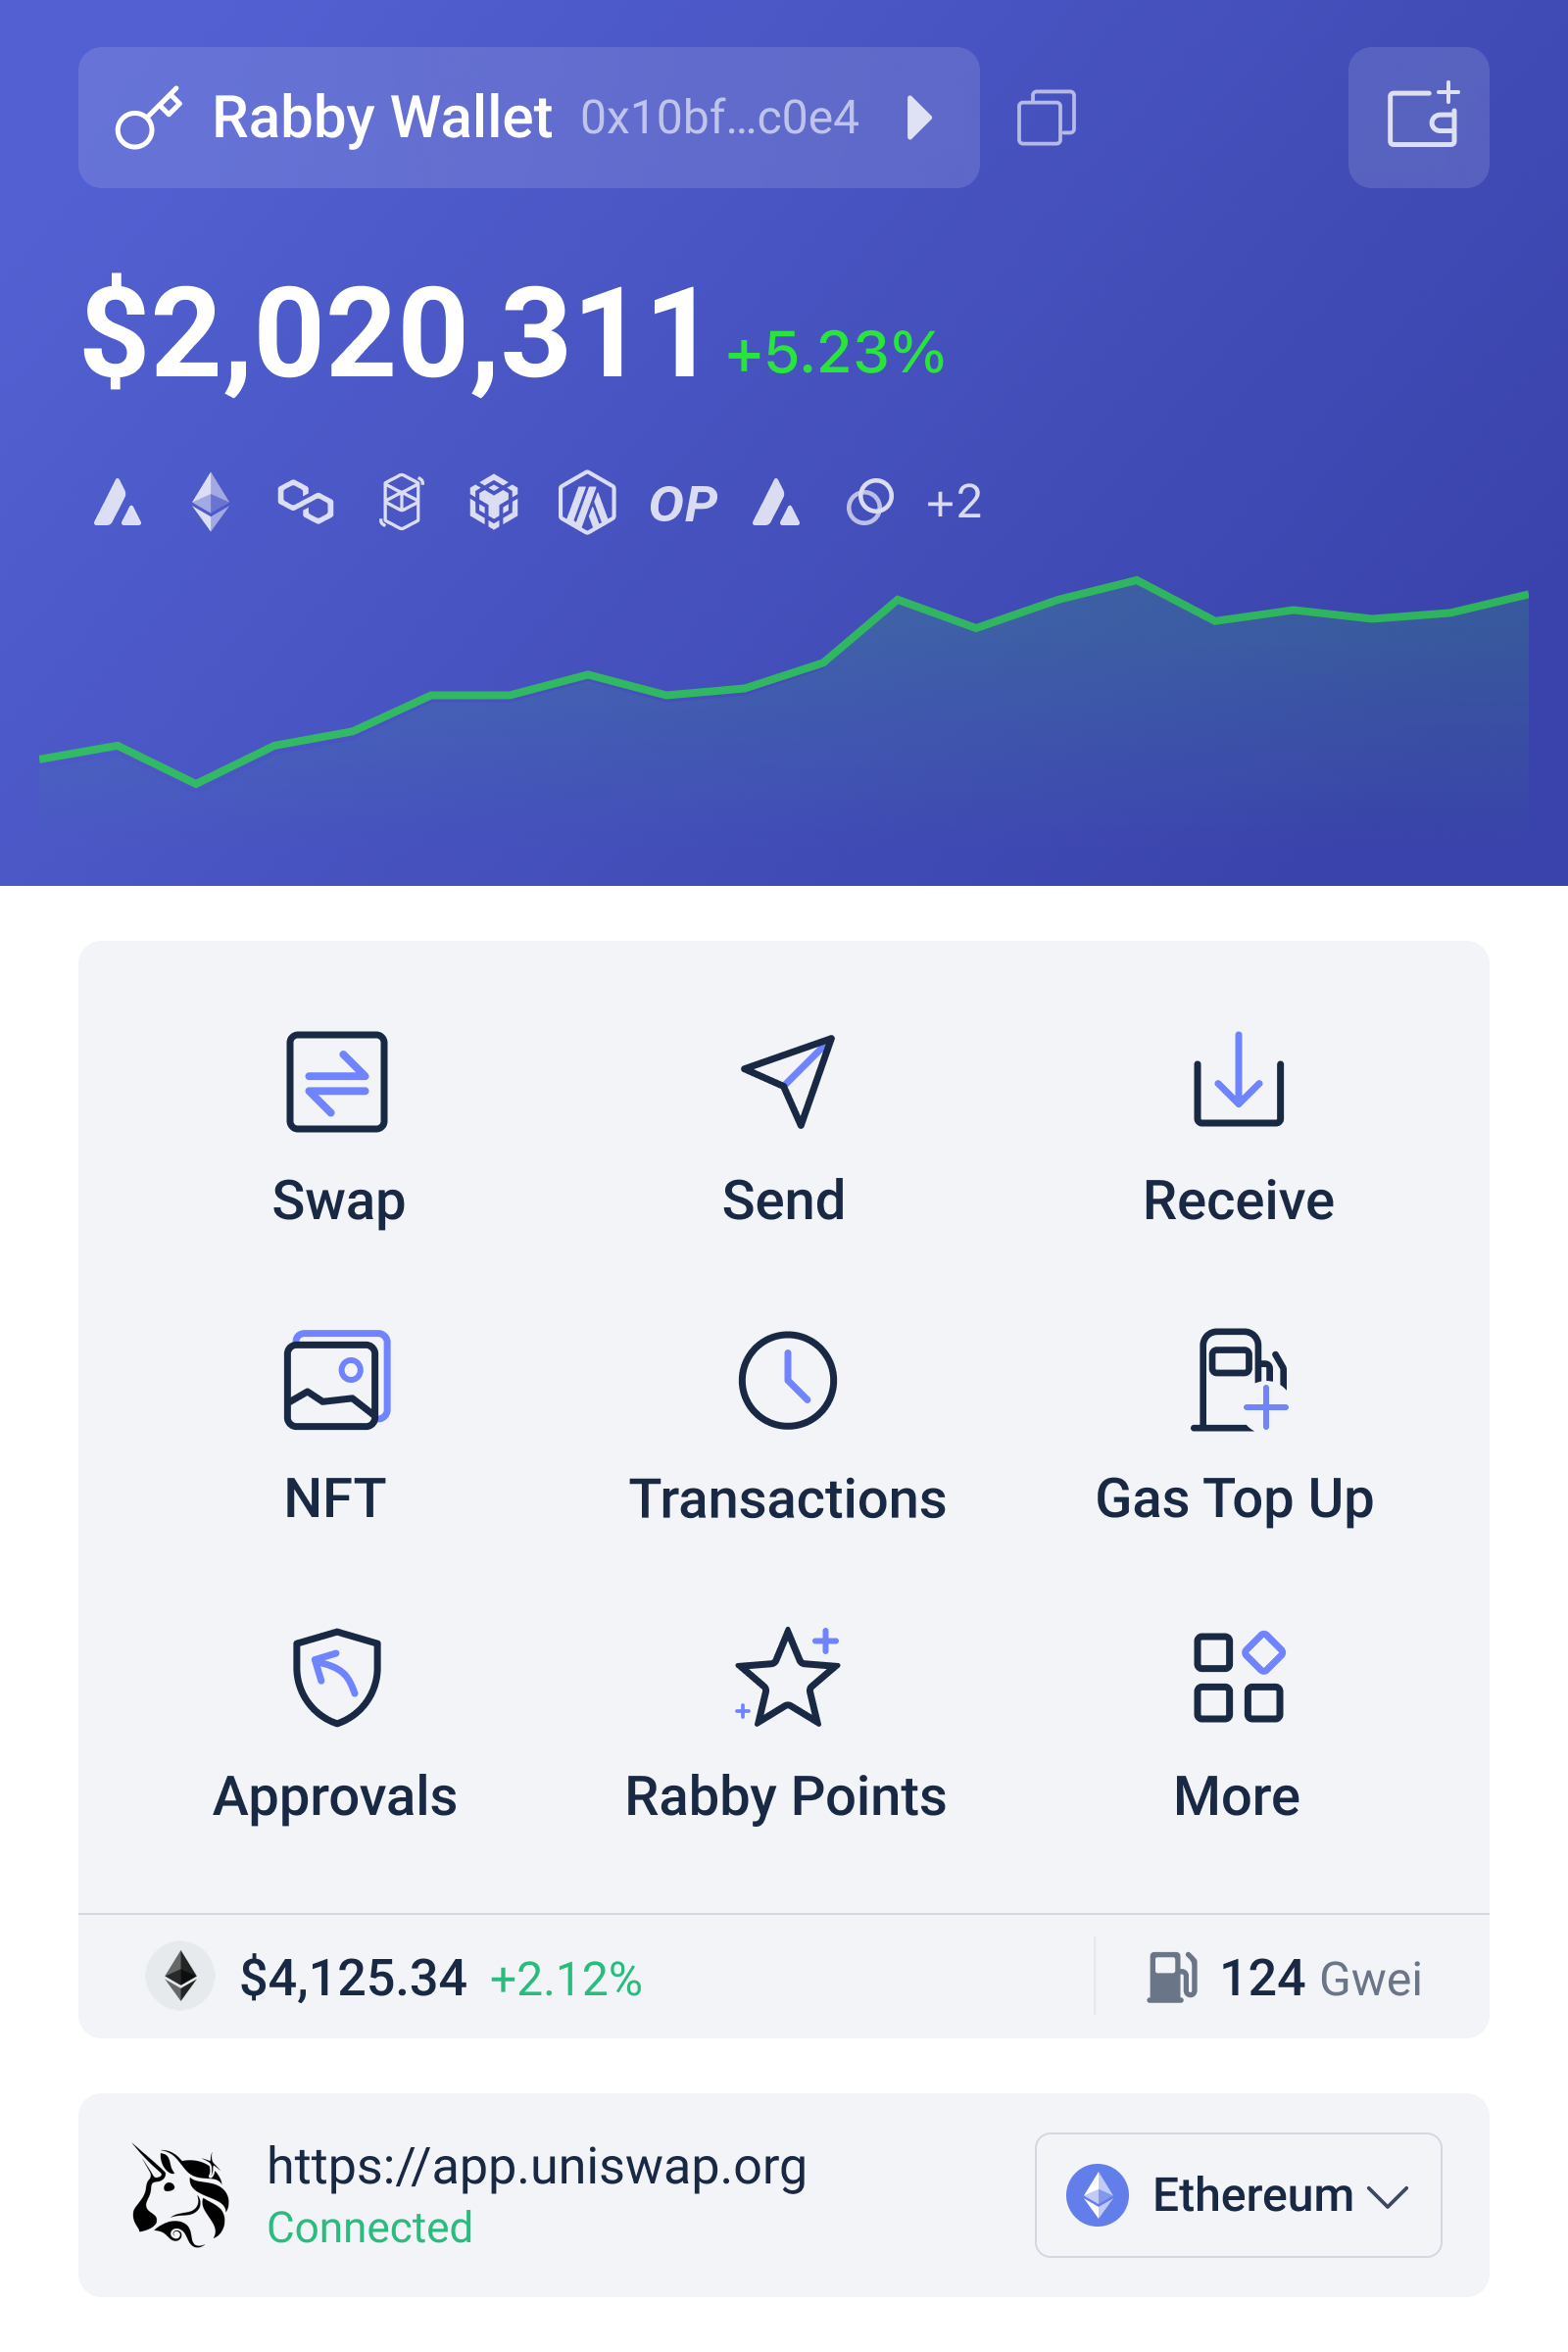
Users evaluating an advanced interface may find value in a rabby wallet workflow that combines multi-chain visibility with transaction-oriented security checks. The useful feature is not branding by itself; it is the opportunity to inspect the relationship between an intended action and its expected portfolio effect before approval. That relationship is where many operational mistakes become visible.
A practical framework for multi-chain portfolio risk
A disciplined review can be organized into four questions: what is owned, what is owed, what has been authorized, and what must continue working? The first question covers balances and positions. The second includes borrowed assets, leverage, margin requirements, and obligations created by liquidity or derivatives protocols. The third covers token allowances, delegated permissions, signed messages, and connected applications. The fourth captures dependencies such as bridges, oracles, sequencers, price feeds, withdrawal mechanisms, and protocol administrators.
This framework produces a more useful portfolio record than a single net-worth number. For each significant position, note the network, contract, economic role, liquidity conditions, exit path, and principal failure mode. A stablecoin position might be exposed to depegging or redemption constraints. A lending position might face liquidation if collateral falls or an oracle updates sharply. A bridge-held asset might depend on message verification and the security assumptions of both source and destination networks.
Risk should also be separated into market risk, protocol risk, and operational risk. Market risk concerns prices, volatility, and liquidity. Protocol risk concerns bugs, governance actions, oracle failures, insolvency, and unexpected contract behavior. Operational risk concerns phishing, address substitution, wrong-chain transactions, excessive approvals, lost credentials, and poor recovery procedures. These categories interact, but they should not be collapsed into one vague score. A low-volatility asset can carry substantial protocol or operational risk.
One reusable heuristic is to compare the value of a position with the cost of exiting it under stress. If an asset is easy to sell in ordinary conditions but depends on a shallow pool or delayed withdrawal process during a crisis, its apparent liquidity is overstated. Similarly, if a user cannot explain how to revoke an approval, migrate a position, or recover access without relying on a single device, the portfolio has a hidden operational liability.
What to monitor as wallet intelligence improves
The recent emphasis on wallets serving Ethereum and EVM networks reflects a broader shift in user expectations. A wallet is no longer merely a key-management container. It increasingly acts as a transaction interpreter, portfolio surface, and security checkpoint. That direction is useful because multi-chain complexity has moved beyond what most users can safely manage through isolated browser tabs and manual record keeping.
The next important development is likely to be better context, not simply more alerts. A warning is valuable when it explains why an action matters: whether the recipient is new, whether an approval is unusually broad, whether the transaction changes collateral exposure, or whether the route introduces another bridge dependency. Too many generic warnings can create alert fatigue, causing users to approve messages mechanically. The quality of interpretation matters more than the number of caution banners.
Users should watch for tools that connect portfolio data to decisions without pretending to predict the market. Useful signals include clearer treatment of protocol positions, allowance inventories, chain-specific transaction outcomes, and scenario-based views of liquidation or withdrawal risk. The open question is how reliably these systems can interpret novel contracts and rapidly changing protocol designs. No interface can compensate for an ecosystem where economic assumptions remain opaque.
For now, the soundest approach is conservative and procedural: separate long-term holdings from experimental positions, use distinct accounts where appropriate, review approvals periodically, verify the network and recipient, simulate material transactions, and keep records of why a position exists. In the United States, where tax reporting may also depend on accurate transaction history, good portfolio structure can support both security review and later reconstruction of taxable activity, although a wallet interface is not a substitute for professional tax advice.
Frequently asked questions
Can a multi-chain wallet accurately measure my total portfolio risk?
No single wallet can measure total risk with certainty. It can consolidate balances, identify transactions and permissions, and expose some dependencies, but valuation may be difficult for illiquid assets and protocol-specific risks may require separate analysis. Treat the wallet as an evidence and verification layer, not as an infallible risk oracle.
Does transaction simulation guarantee that a DeFi transaction is safe?
No. Simulation can show the likely state changes under a particular network state, helping reveal unexpected transfers, approvals, or position changes. It cannot guarantee that a contract is bug-free, that market conditions will remain unchanged, or that every off-chain signature and future permission will be harmless.
What should I review first when managing several EVM chains?
Start with permissions and dependencies, then review balances. Identify broad token approvals, unfamiliar connected applications, bridge exposure, borrowed positions, and assets that cannot be exited quickly. After that, verify whether the portfolio’s displayed value depends on assumptions that would fail during high volatility or reduced liquidity.
The strongest portfolio-tracking habit is therefore not checking a number more frequently. It is learning to see a wallet as a system of assets, rights, obligations, and dependencies. When tracking is combined with transaction simulation and deliberate permission management, the user gains something more valuable than a prettier dashboard: a clearer view of how capital can be lost, how errors can be caught, and which assumptions deserve renewed scrutiny before the next signature.